Understand the county revenue gap
Use the analysis as context for reviewing your own revenue streams, collection performance, and rollout priorities.
Explore county revenue collection workflows, from billing and payment references to reconciliation and reporting. Request an ICRMS evaluation tailored to your county.
Illustrative workflow
Fictional records for illustration. Confirm the workflow in your tailored demonstration.
County revenue teams need traceable bills, receipts and exceptions across revenue streams. Start with the county’s approved charges, collection procedures and reporting responsibilities.
Disconnected registers make it difficult to reconcile bills and receipts.
Unidentified payments and reversals need controlled resolution.
Revenue targets must be evaluated alongside comparable collection evidence.
We will match the discussion to your organization. Confirm demonstrated capabilities, configuration needs and external dependencies in the proposal.
Map revenue streams, customer references, approved charges, adjustments and responsible officers.
Review payment allocation, settlement checks, duplicate handling and reversal workflows across agreed channels.
Discuss field devices, receipt verification, access permissions and the required connectivity or downtime procedures.
Agree daily reconciliation, exception queues and management reporting with the finance team.
Use the CRA Standards and Guidelines on ICRMS, Gazette Notice 12835 of 9 September 2025, as a source for requirements review. Confirm current applicability and any subsequent instruments.
Define migration checks, officer training, support arrangements and acceptance evidence for a phased rollout.
Agree who prepares, reviews and approves each operational step.
Include incomplete, disputed and reversed transactions in the evaluation.
Use your baseline and agreed test cases to assess the implementation.
Confirm officer training, support contacts and fallback procedures before live collections.
Start with the register and fee schedule, then follow the bill, receipt and reconciliation decision. A useful evaluation shows who can act on each record and how exceptions reach an accountable reviewer.
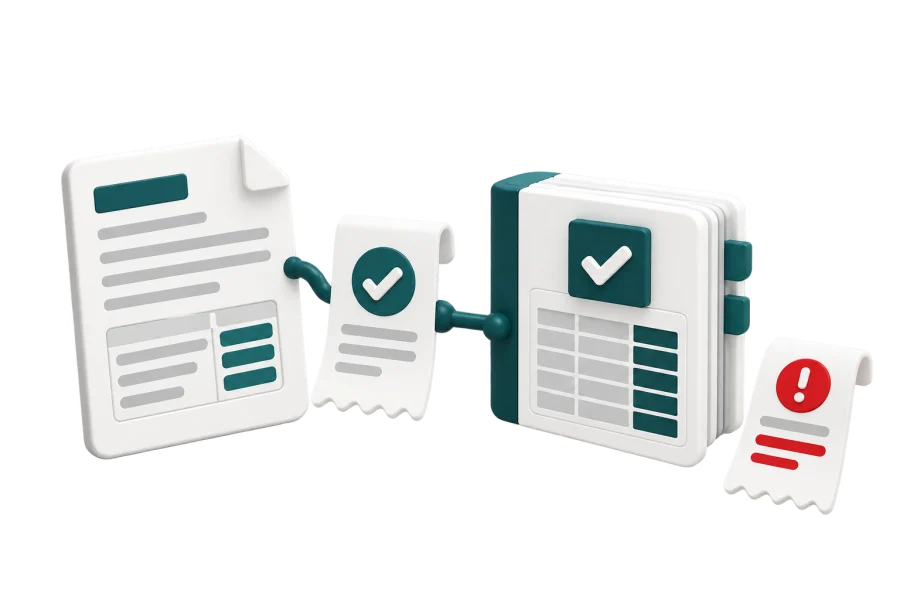
Illustrative example using synthetic data; not a customer result or a statement of verified product behavior.
For fictional bill BILL-1048, record the revenue stream, ward or collection point, fee-schedule version and effective date. Use KES 5,000 as the worked obligation, not an official county tariff.
A KES 3,000 payment leaves KES 2,000 outstanding. Ask to see both records and the allocation linking them; a payment notification alone does not explain the remaining obligation.
Keep receipt RCT-2082, KES 700, unallocated while its bill reference is missing. Assign it to a reconciliation officer, record the investigation and follow the configured verification and approval steps. It must not reduce BILL-1048 without an authorized allocation.
Filter the report by period, stream, channel and collection location, then trace a total to its source receipts. Keep received, allocated and bank-settled amounts distinct; a repeated payment notification should be tested for a single financial effect.
Distinguish the Treasury’s June 2025 draft-regulation consultation from the CRA Standards and Guidelines published in Gazette Notice 12835 on 9 September 2025. Confirm applicable requirements and later amendments with the responsible county advisers.
No. Results depend on the revenue base, targets, implementation, staffing and operating conditions. Agree a comparable baseline and measure collection, reconciliation and service outcomes.
Bring representative transactions, exception cases and reporting requirements to the demo. Ask for evidence against each requirement and agree acceptance criteria before procurement.
Identify billing registers, outstanding balances and payment references to bring into the system. Agree data ownership, cleanup and reconciliation checks, then validate a sample import before approving the opening balances.
If water-related collections are part of your scope, map the handoff between billing records, payment reconciliation, and service follow-up. Confirm the responsibilities of the county and relevant service provider during discovery.
Explore solutions for water and environment departmentsUse the analysis as context for reviewing your own revenue streams, collection performance, and rollout priorities.
Use the guide and referenced sources to prepare questions for your revenue-system evaluation.
Evaluate an integrated county revenue management system (ICRMS) against the billing, collection and reconciliation work your county actually performs. Compare a complete transaction trail, not just a payment screen.
Scope the revenue streams, billing rules, payment channels, receipting, reconciliation, exception handling and reports together. Confirm demonstrated workflows and implementation dependencies in the proposal.
Define the county operational workflows and the required relationship with national financial processes. Agree interfaces, responsibilities and approvals; do not assume that a new revenue system replaces IFMIS.
Share your county, revenue streams, users, collection locations, payment channels and migration requirements. Request a proposal that separates implementation, support and any external integration dependencies.
ROI Calculator
Run the full CountyERP Revenue Impact Calculator to estimate annual value across revenue, licensing, health, HR, and procurement.
Share your organization, product interests and rollout priorities for a tailored walkthrough or proposal.